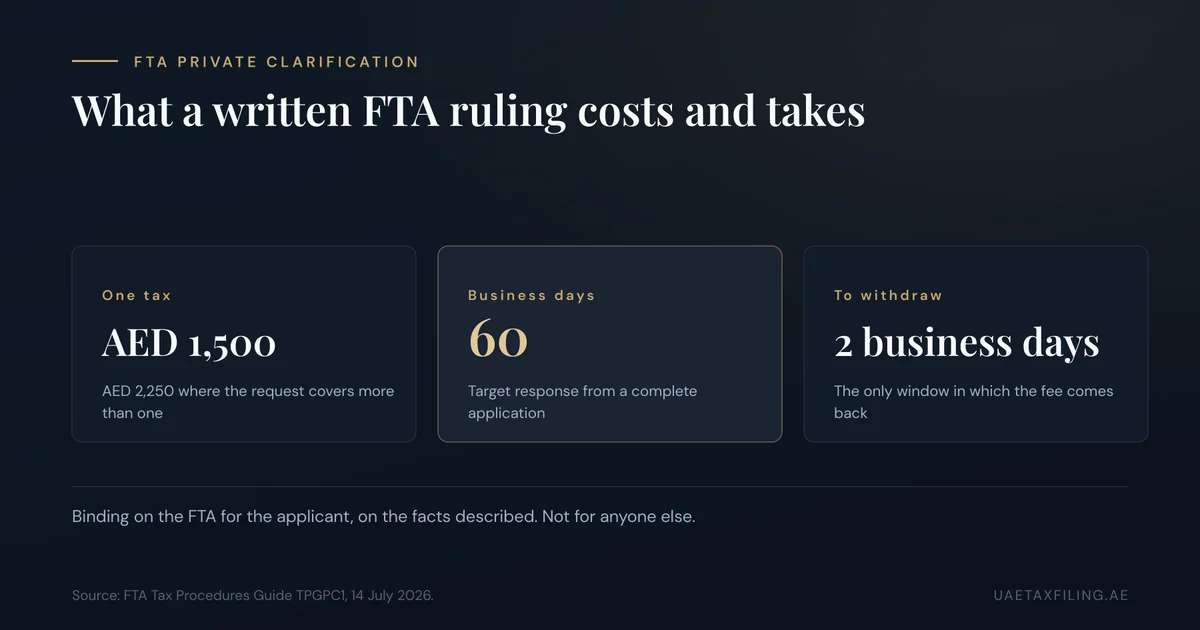
FTA Private Clarifications: When to Pay AED 1,500
A private clarification costs AED 1,500 and takes 60 business days. What the 14 July 2026 guide changed, the eleven published rejection grounds, and when the free route answers the same question.
How to Value a Deemed Supply of Services
FTA Directive 5 of 2026 sets the method for valuing a deemed supply of services: strip out profit, then strip out costs that never carried input tax. On a AED 100,000 service that can halve the VAT.
Who Counts as a Director or Officer for UAE Tax
FTA Clarification CTP010 defines director and officer for Article 36. Board seats, real authority, the job-title trap in both directions, and why it caps what you can deduct for their pay.
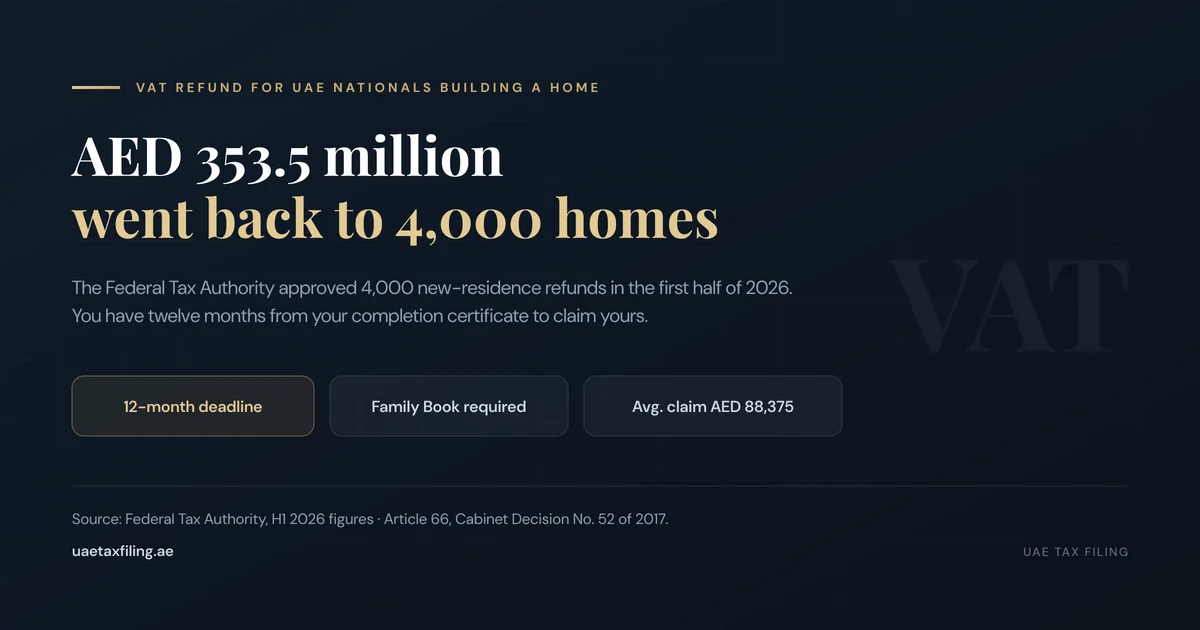
VAT Refund for UAE Nationals Building a Home
UAE nationals can reclaim VAT on building a new home. AED 353.5 million went back to 4,000 applicants in H1 2026. Eligibility, what qualifies, the two deadlines and the invoice rules that cause rejections.
Free Zone Distributors Now Need a Second Report
FTA Decision 6 of 2026 requires Qualifying Free Zone Persons distributing goods in or from a Designated Zone to obtain an ISRS 4400 agreed-upon procedures report. Scope, evidence, sampling formula and the 30-day deadline.
New UAE Input Tax Rules Start 1 October 2026
From 1 October 2026, FTA Decision 13 of 2026 requires UAE businesses to verify every supplier and supply before deducting input tax. The thresholds, the checks, and the written policy you now need.
UAE Corporate Tax Record Keeping Requirements
Every UAE taxable person must keep records for seven years from the end of the tax period. What to keep, which accounting standard applies at your revenue level, and the two separate penalties for getting it wrong.
Qualifying Group Relief & Restructuring in the UAE
Move assets or a whole business between UAE companies with no gain, no loss. A clause-level guide to Qualifying Group Relief, Business Restructuring Relief, the election, and the two-year clawback.
How to Waive the AED 10,000 Corporate Tax Penalty
Fined AED 10,000 for late UAE Corporate Tax registration? There is a built-in way to have it waived, and refunded if you already paid, plus three fallback routes if you miss the window.
VAT on Digital Services in the UAE
UAE VAT on digital and electronic services is charged at 5% where the service is used and enjoyed here. A clause-level guide to reverse charge on foreign SaaS, non-resident registration, and zero-rated exports.
How UAE Family Foundations Are Taxed
How UAE family foundations are taxed: taxed like a company by default, but able to elect tax transparency under Article 17 so income flows to beneficiaries.
Export of Services and UAE VAT: When 0% Actually Applies
A UAE service export is zero-rated only if four conditions hold at once. Since 15 November 2024 the place of supply is tested first, and it closes the export route more often than most businesses realise.